What is the difference between a site condo and an unwarrantable condo when getting a mortgage in Michigan?
In Michigan, a site condo is a detached single-family home under a condominium master deed and usually qualifies for standard Conventional, FHA, or VA financing. An unwarrantable condo is a unit in a community that falls outside standard Fannie Mae or Freddie Mac rules (such as high investor concentration or commercial space) and requires a lender with specialized unwarrantable condo options. Our Grand Rapids office reviews the association master deed upfront so you know immediately whether your unit qualifies for standard agency financing or our specialized unwarrantable condo program.
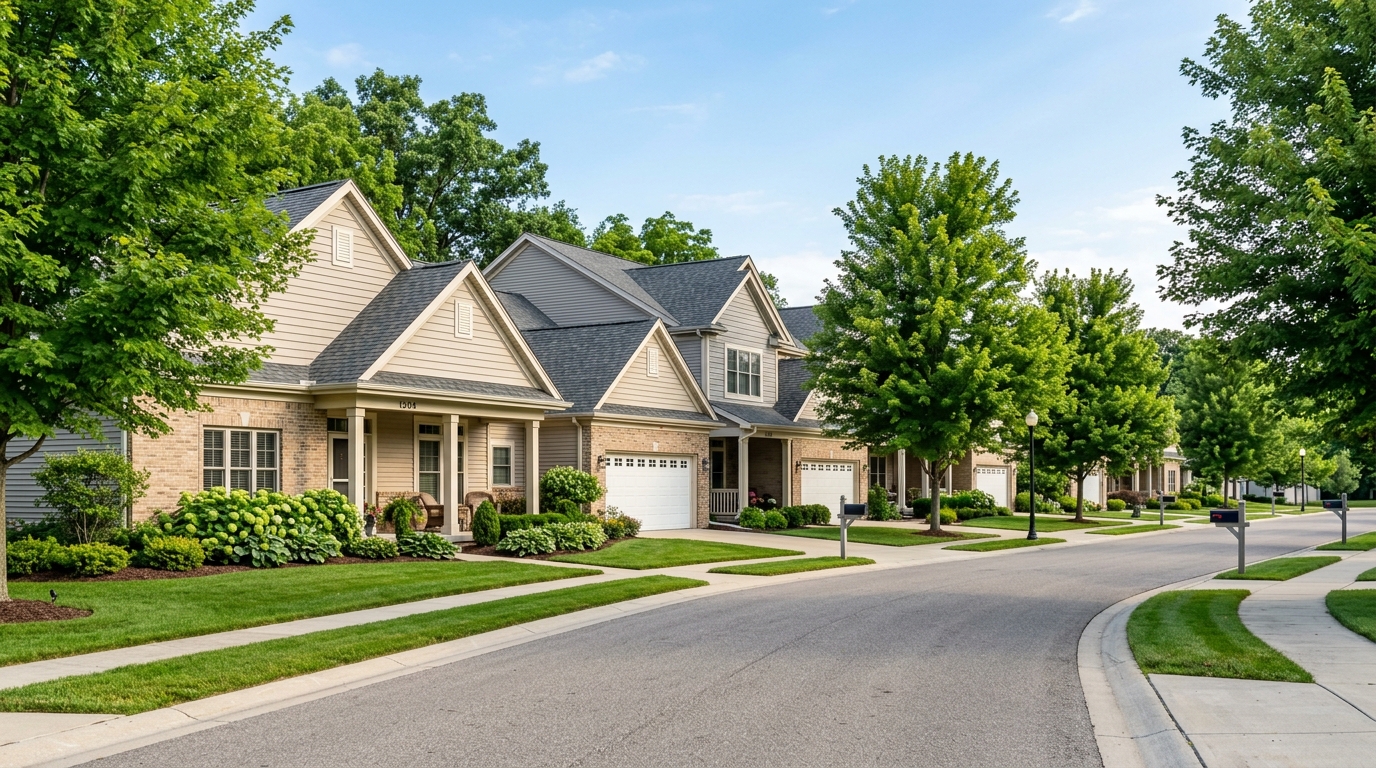
If you have been browsing listings around Caledonia, Hudsonville, Ada, or downtown Grand Rapids, you have probably noticed standalone single-family houses with yards and driveways that are listed in the MLS as ‘Site Condos’—right alongside downtown high-rises and attached townhomes.
Out-of-state call-center lenders routinely panic when they see the word ‘condominium’ on a Michigan purchase agreement, ordering unnecessary HOA questionnaires or turning down great properties late in underwriting because they don’t understand how Michigan condo laws work.
Planning a condo or site condo purchase? Run your numbers on our Home Purchase Payment Calculator or review our Michigan Loan Options Overview.
How Underwriters Separate Site Condos From Attached Condo Buildings
When buyers ask “What is the difference between a site condo and an unwarrantable condo when getting a mortgage in Michigan?”, the distinction comes down to how the physical property and the homeowner association (HOA) are structured. In Michigan, developers frequently use a Condominium Master Deed instead of a traditional subdivision plat to build neighborhoods of completely detached, single-family homes—known as site condos.
Under agency guidelines (including Fannie Mae Selling Guide B4-2.1-01), a detached site condo where the buyer owns the standalone structure and lot is underwritten just like a traditional single-family home. Attached condos and townhomes, however, share roofs, walls, and master hazard insurance—meaning the association itself must pass a “warrantability” review unless you use a specialized unwarrantable condo program.
Have Your Eye on a Specific West Michigan Condo?
Before you submit an offer, our Grand Rapids team can check whether the development is a detached site condo, a warrantable association, or eligible for our unwarrantable condo financing.
Comparing Condo Financing Paths in Michigan
Not every condo in West Michigan is underwritten the same way. Here is how our team evaluates each type of condo property and loan option side by side:
| Condo Property Type | How It Is Structured | Available Loan Programs | How Our Team Helps |
|---|---|---|---|
| Detached Michigan Site Condo | Standalone single-family house and lot governed by a condominium master deed | Conventional (3%+ down), FHA (3.5% down), VA ($0 down), and MSHDA | Underwritten like a traditional single-family home without full HOA building questionnaires |
| Warrantable Attached Condo (Conventional) | Townhome or attached unit in an association meeting Fannie Mae / Freddie Mac reserve rules | Conventional (3% to 20%+ down) and MSHDA | We verify HOA reserves (10%+ budget allocation) and master insurance upfront |
| FHA or VA Approved Attached Condo | Attached condo unit in an FHA/VA-approved project or eligible for Single-Unit Approval | FHA (3.5% down) or VA ($0 down) | Our team checks HUD/VA project approval or coordinates an FHA Single-Unit spot review |
| Unwarrantable Attached Condo | Association with higher investor/rental ratios, new construction phases, or unique HOA rules | Specialized Unwarrantable Condo Loan | When standard banks decline the building, our dedicated unwarrantable program keeps your purchase moving |
Three Condo Financing Rules Every Michigan Buyer Should Know
Understanding how lenders evaluate different condo developments in West Michigan protects your earnest money and keeps your closing on schedule:
- Detached Michigan Site Condos Skip the Red Tape: Because a detached site condo has no shared walls or shared structural elements, it qualifies for standard Conventional (3%+ down), FHA (3.5% down), VA ($0 down), and MSHDA financing without requiring a lengthy HOA project questionnaire or condo fee add-ons.
- What Makes an Attached Condo “Warrantable”: For traditional townhomes and mid-rise condos, Fannie Mae and Freddie Mac verify that the association allocates at least 10% of its annual budget to capital reserves, carries adequate master insurance, has no single entity owning too many units, and has no active structural litigation.
- How Our Unwarrantable Condo Loans Save Deals Other Lenders Reject: If a downtown Grand Rapids loft, lakeshore association, or newly built condo phase has higher rental/investor ratios, short-term rental permissions, or incomplete construction phases, standard banks will decline it as “unwarrantable.” Our office offers dedicated unwarrantable condo loan options so you can still purchase the unit with confidence.
Let Our Team Verify Your Condo Association Upfront
Don’t wait until two weeks before closing to find out how a lender views an HOA. Connect with our team and we will review the property address and association details upfront so your offer is rock-solid.
Continue Exploring
Compare related Michigan mortgage guides and interactive calculators below:
- Turned Down for a Mortgage? Exploring Your Options in Grand Rapids — How reviewing your application with an experienced local team can uncover program options or practical next steps.
- What Mortgage Underwriters Are Looking For — A behind-the-scenes look at how underwriters verify credit, income, assets, and property guidelines.
- Timeline Trouble: What Causes Delays in Closing—and How to Avoid Them — How proactive upfront underwriting and local appraisal coordination prevent last-minute closing delays.
- Interactive Home Purchase & Payment Calculator — Compare side-by-side home purchase scenarios, Michigan homestead vs. non-homestead property tax settings, and custom loan terms.
Mortgage One Grand Rapids • 3243 East Paris Ave. SE, Kentwood
Let’s Walk Through Your Options Together—No Pressure, Just Clarity
You don’t have to piece this together alone on a generic calculator. Whether you’re six weeks or six months away from making a move, our local team will gladly review your goals and give you clear options so you can move forward with total confidence.